


Foreign portfolio investors could see improved post-tax returns if India scraps or reduces capital gains tax, but the move is unlikely to trigger a meaningful revival in foreign inflows on its own, according to brokerage assessments published this week.
A October 30 report from JM Financial noted that while a cut in long-term capital gains tax (LTCG) or short-term capital gains tax (STCG) could boost post-tax returns and signal a more investor-friendly policy environment, taxation is not the primary driver of foreign portfolio flows. Valuations, currency movements and relative opportunities across emerging markets are likely to matter more. JM Financial estimates that scrapping LTCG tax could add around 2.2 percentage points to an average year's dollar returns for foreign investors, broadly offsetting the annual drag from rupee depreciation. However, the brokerage noted that valuation changes can have a much larger impact: a one-time expansion of the market's price-to-earnings multiple by one turn could boost returns by 5.8 per cent, and a re-rating from the current 17.1 times to the 10-year average of 21.3 times would imply a potential gain of 24.3 per cent. The report estimates such relief could add $3-5 billion to foreign inflows in FY28 under its bull-case scenario.
Bernstein echoed this assessment in an October 19 report, stating that a reduction in LTCG tax would be desirable for a capital-starved economy but would not, by itself, trigger sustained foreign institutional investor inflows. The brokerage also highlighted that FPIs currently pay 12.5 per cent LTCG and 20 per cent STCG on listed Indian equities in rupee terms, excluding applicable surcharge and cess.
JM Financial has suggested alternatives to scrapping LTCG altogether, including taxing FPIs on dollar-denominated gains instead of rupee-denominated gains, or indexing acquisition costs to account for rupee depreciation. Other options include bringing the STCG rate closer to the LTCG rate or reducing the 12-month holding period required for long-term capital gains treatment for FPIs.
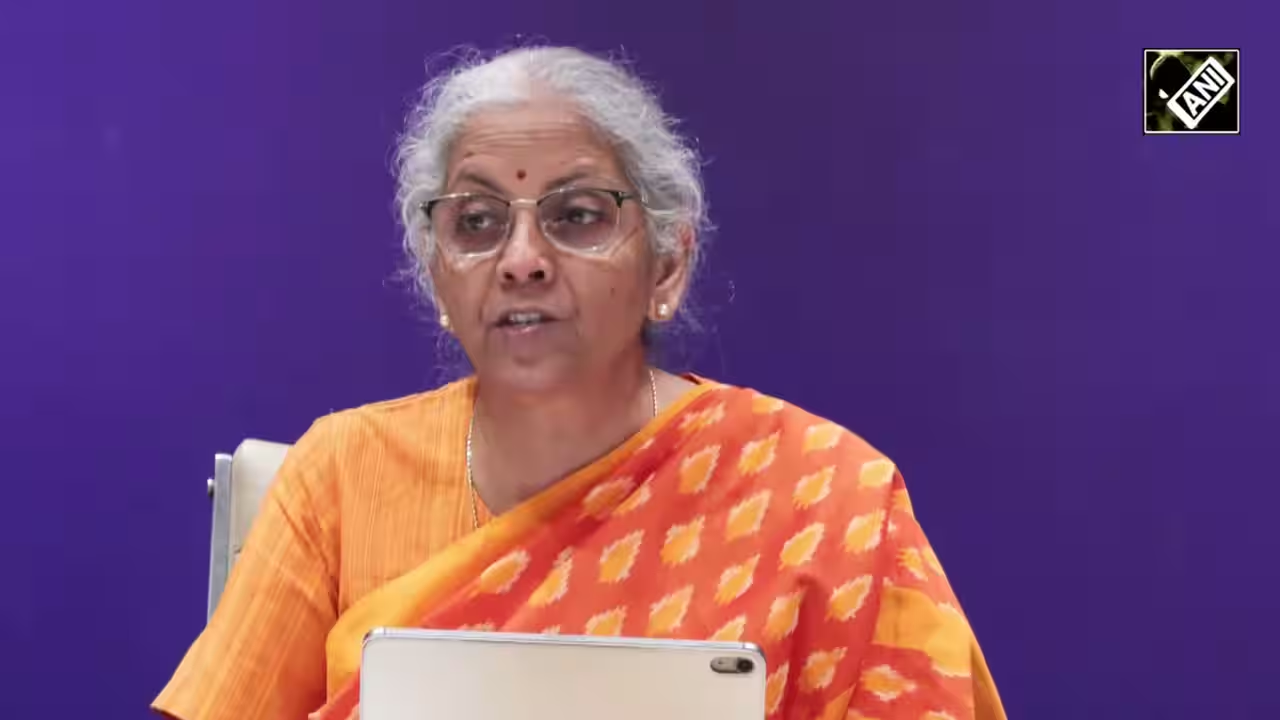
Finance Minister Nirmala Sitharaman acknowledged concerns raised by foreign investors over India's tax structure on November 2, stating she would consider the feedback ahead of the Union Budget. She noted that India's taxation structure was broadly similar in 2023-24 when the country witnessed strong foreign investment inflows without additional tax incentives. Sitharaman stopped short of committing to changes to equity taxation, but said she recognises the voice of market participants. Separately, a Reuters report from October 2 indicated that the Securities and Exchange Board of India has recommended the government remove the LTCG tax imposed on foreign investors.
SBI Research reported that the Centre has sufficient fiscal space to absorb the revenue loss from abolishing long-term capital gains tax, with the potential impact estimated at Rs 40,000-50,000 crore in FY28. The report estimates LTCG tax collections could fall to Rs 40,000-50,000 crore in FY27 from approximately Rs 1 lakh crore in FY26 and Rs 1.29 lakh crore in FY25, noting the government would be able to take this hit within its fiscal consolidation roadmap given likely declines in capital gains tax collections amid subdued stock market returns.
The issue assumes importance amid concerns over sustained foreign portfolio outflows, market volatility and the relative attractiveness of Indian equities compared with other emerging markets. While tax relief could serve as a positive policy signal, the consensus among analysts is that sustained FPI flows will depend more on valuation attractiveness, earnings outlook and macroeconomic fundamentals than on capital gains tax rates alone.